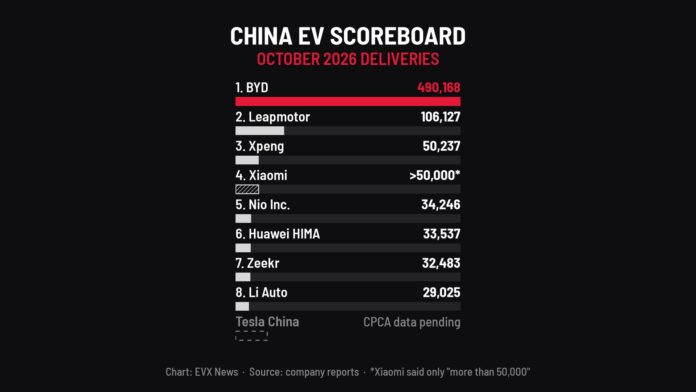

BYD delivered 490,168 new energy vehicles in October, more than the next seven Chinese EV makers on our list combined. Leapmotor stayed a clear No. 2 at 106,127, Xpeng and Xiaomi both crossed 50,000, and Nio, Huawei’s HIMA alliance, Zeekr and Li Auto all slipped from September.
This is our monthly scoreboard: one table, every major brand, with month-on-month and year-on-year changes worked out from the companies’ own figures. We covered BYD’s record battery-EV month and the first reactions last night. Here is the full ranking.
The October 2026 table
| # | Brand | Oct 2026 | Sep 2026 | MoM | Oct 2025 | YoY |
|---|---|---|---|---|---|---|
| 1 | BYD (all NEVs) | 490,168 | 463,561 | +5.7% | 441,706 | +11.0% |
| 2 | Leapmotor | 106,127 | 105,656 | +0.4% | 70,289 | +51.0% |
| 3 | Xpeng | 50,237 | 41,256 | +21.8% | 42,013 | +19.6% |
| 4* | Xiaomi | >50,000 | 40,015 | at least +25.0% | 48,654 | at least +2.8% |
| 5 | Nio Inc. (Nio, Onvo, Firefly) | 34,246 | 37,408 | −8.5% | 40,397 | −15.2% |
| 6 | Huawei HIMA | 33,537 | 37,490 | −10.5% | 68,216 | −50.8% |
| 7 | Zeekr | 32,483 | 37,216 | −12.7% | 21,423 | +51.6% |
| 8 | Li Auto | 29,025 | 31,817 | −8.8% | 31,767 | −8.6% |
| – | Tesla China (CPCA wholesale) | pending | 95,366 | – | 61,497 | – |
Figures are company-reported October deliveries (BYD: sales). BYD and Leapmotor include exports. *Xiaomi said only “more than 50,000,” so its change is a minimum and its exact rank versus Xpeng is unknown until the China Passenger Car Association (CPCA) publishes the exact number. Prior-month and prior-year figures are the companies’ own reported numbers; percentages are our calculations.
BYD: a different weight class
BYD’s Hong Kong exchange filing breaks the 490,168 down like this:
- Battery-electric passenger cars: 305,743, up 37.4% from a year earlier and 11.9% from September
- Plug-in hybrid passenger cars: 177,382, down 17.2% year on year and 3.4% month on month
- Commercial vehicles: 7,043
- Exports: 170,194, up 102.8% year on year but 5.8% below September
That puts battery EVs at 63.3% of BYD’s passenger car sales. Sales in China were 319,974, down 10.6% from a year earlier, so the year-on-year growth came from abroad. Cailian Press, Sina Finance and D1EV carried the same filing numbers. The same export push was behind BYD’s 28% jump in third-quarter profit.
The startups: who moved
Leapmotor topped 100,000 for a fourth straight month, but it grew only 471 cars from September. It is at 772,666 for the year against a 1 million target, which means it needs about 113,700 a month in November and December.
Xpeng jumped 21.8% from September to its first month above 50,000, the biggest confirmed month-on-month gain on the board (only Xiaomi’s “at least 25%” could top it). Overseas deliveries hit a record 13,326, about 26.5% of the total.
Xiaomi posted its best month of 2026 on its official Weibo account, helped by the first full month of its Sky Nomad range-extender series. Because it gave a floor rather than a number, we can’t say yet whether it beat Xpeng.
Nio Inc. fell 15.2% year on year, its first annual drop since February 2024. The split tells the story: the Nio brand did 18,125 (up 5.7%), Firefly hit a record 7,738 (up 30.9%), and Onvo fell to 8,383 (down 51.7%).
Huawei’s HIMA alliance had the worst year-on-year number on the board, down 50.8% to 33,537. HIMA, whose brands include AITO, Luxeed, Stelato and Maextro, didn’t give a brand breakdown for October. Zeekr fell 12.7% from September, ending a six-month record run, while still up 51.6% on a year ago. Li Auto was down both ways and closed out the table at 29,025, though it said more than 3,000 of those were the new Mega.
Tesla China: still waiting on CPCA
Tesla doesn’t publish a China monthly number itself. Its Shanghai figure comes from the CPCA’s preliminary report, which hadn’t been released when this was published. For reference, Shanghai wholesale was 95,366 in September, its best month of 2026, with 30,529 exported and 64,837 sold in China, and 61,497 in October 2025, according to CPCA data compiled by CnEVPost. Tesla China has halved its down payment and added 0% financing on the Model 3 and Model Y to get domestic sales going, and the Model Y was China’s best-selling car in September. We’ll add Tesla to this table when the CPCA number lands.
The EVX Take
The pattern this month is simple: the brands growing fastest either had a new model or a strong export pipeline (BYD, Xpeng, Leapmotor), while the brands relying mostly on China’s soft home market went backward. That matters for Tesla because the CPCA wholesale figure mixes Shanghai exports with domestic sales, and Shanghai also builds the Model 3 and Model Y that Japan gets. A strong export month from Shanghai is good news for Japanese delivery times, even if it hides weaker China retail. For BYD Japan, the contrast is stark. BYD sold close to half a million cars in a month, but its Japan sales were still under 1,000 in September, even counting the new Racco kei car, according to the Japan Automobile Importers Association and the Japan Mini Vehicles Association. That’s not BYD failing in Japan. It’s BYD not needing Japan, while its 170,000 monthly exports compete with Toyota, Honda and Nissan in the markets where they make their money.
JAIA’s October import registrations come out in early November, and CPCA’s exact Xiaomi and Tesla numbers should follow soon after. Both go in this scoreboard’s next update.
Sources: BYD HKEX filing (Oct. 2026 production and sales), Cailian Press (BYD), Sina Finance (BYD filing), D1EV (BYD), Eastmoney (startups, from company Weibo posts), Sina Finance (startups), iFeng Auto (roundup), China Securities Journal (via Sina), National Business Daily (Zeekr), Yicai (HIMA), Sina Finance (HIMA, Zeekr, Nio), CnEVPost (roundup and prior-period data), CnEVPost (Tesla China September), Money1 (JAIA and Zenkeijikyo September data).
— The EVX News team
Featured image: Chart: EVX News, from company-reported October 2026 delivery figures.

